Lifted shingles, missing ridge caps, a tarp that needs to go on today. AEVO Pro is a veteran-owned Florida roofing company, in business since 1977, with crews in the Panhandle now. We tarp it, document it for your claim, and repair or replace it.
Who we are
AEVO Pro is a veteran-owned, licensed and insured Florida contractor. We have worked residential and commercial roofs across Florida, Georgia, the Carolinas, Louisiana and Texas since 1977, and we have crews staged in Milton and Destin for the length of this recovery. Every inspection is free, every estimate is itemized, and every job is documented the way an insurer needs to see it.
Shingle, metal, tile and flat systems on single-family homes, townhomes and condos. Storm repair and full replacement.
Low-slope and metal roofs on retail, office, church and multi-family buildings. Emergency dry-in so you can stay open.
Tarping, temporary dry-in and leak stops, photographed and receipted so the insurer sees you prevented further damage.
What we do
Properly anchored tarps over lifted, torn and missing sections so the next rain stays out while the claim moves. Photographed and receipted for the file.
Lifted and creased shingles, missing ridge caps, torn flashing, punctures from debris, bent drip edge. Fixed to code, not patched.
When the insurer's scope or Florida's building code calls for a full replacement rather than a patch, we handle it under the same claim.
Where the water actually got in, how far it traveled, and what it soaked on the way down. Moisture-mapped, not guessed.
Architectural shingle, standing-seam metal, concrete and clay tile, modified bitumen and TPO on low-slope roofs.
Photos, moisture readings and an itemized scope written the way the carrier reads it, so the roof claim gets paid for what is actually there.
What the storm did

Wind gets under the edge of a shingle, creases the tab, breaks the seal strip, and lays it back down. From the street the roof looks fine. From the attic, every rain since October 9 has been coming through the underlayment into the decking and the insulation.
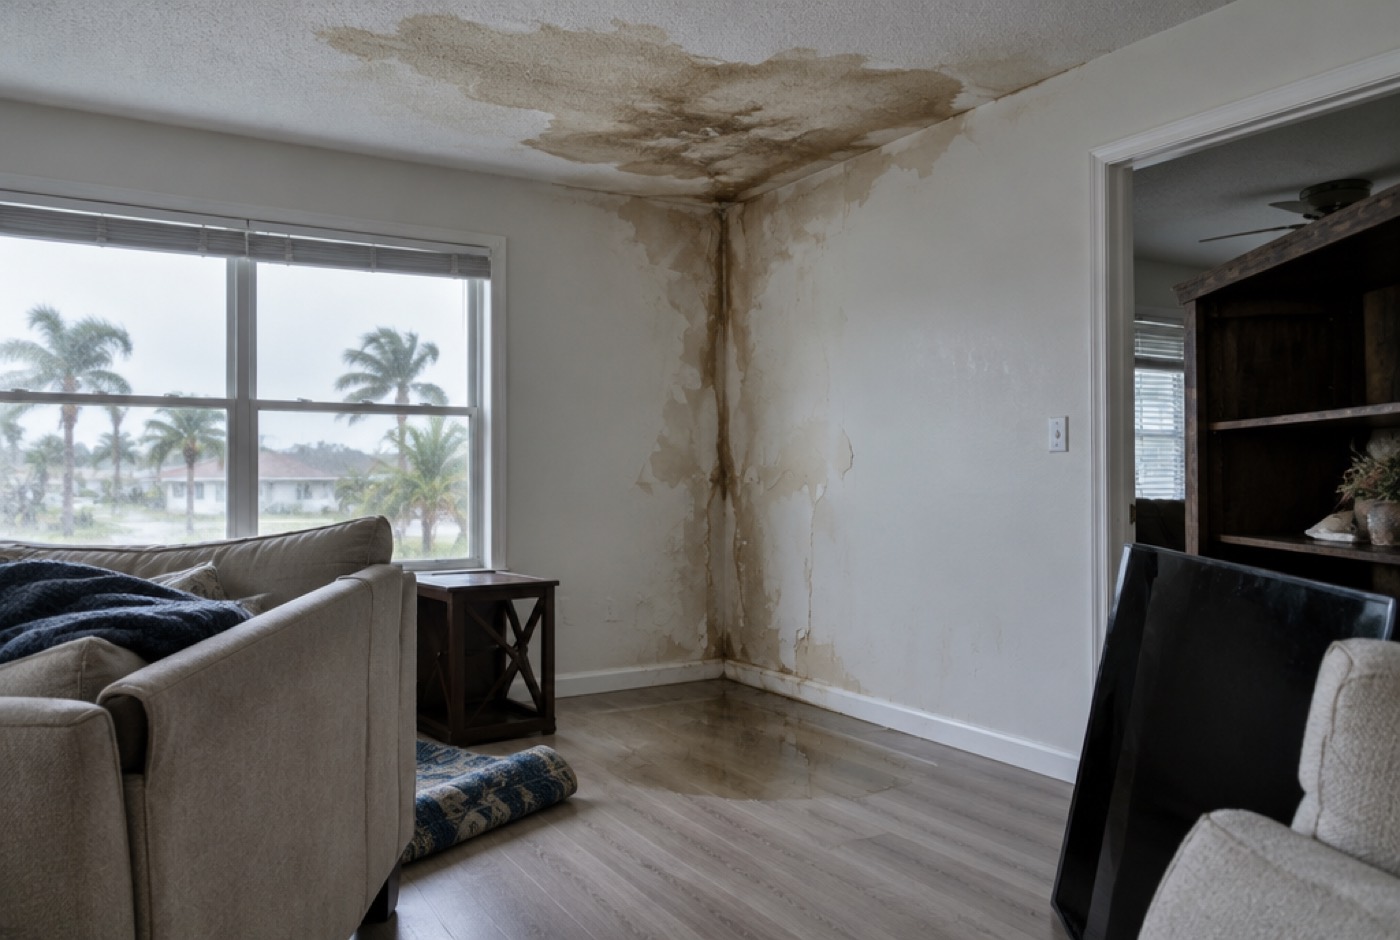
Wet insulation holds water for weeks. It shows up as a ceiling stain, then bubbling paint, then a sag. By then the decking under the shingles is soft, and a repair that would have been a few squares becomes a section of roof.
If you are not sure whether your roof was hit: that is exactly what the free inspection is for. We look from the roof and from the attic, and we tell you honestly if there is nothing to claim.
How it works
Four steps, one crew, one itemized scope from the first visit to the last shingle.
You tell us what you are seeing. We tell you what to do in the next hour and schedule the inspection.
Roof and attic. Photos, moisture readings and an itemized damage report, written the way an insurer reads it.
Emergency tarp or dry-in over the damaged section, photographed and receipted. The damage stops getting worse.
Scoped against your policy, permitted, built to the Florida Building Code, and documented for the claim. Deadline for notice on this storm: October 9, 2027.
Where the crews are working
Milton, Pace, Gulf Breeze, Navarre, Jay and the communities north of I-10 that took the heaviest debris.
Destin, Fort Walton Beach, Niceville, Crestview, Mary Esther and Shalimar, from the landfall point inland.
Pensacola, Pensacola Beach, Cantonment, Perdido Key and the neighborhoods that saw the strongest gusts.
Roof questions people are asking this week
If shingles are lifted, creased or missing, yes. The underlayment is exposed and the next rain goes into the decking. Your policy also requires reasonable steps to prevent further damage, and a tarp is the step the insurer expects to see. Keep the receipt.
Under Florida Statute 627.70132 you must give notice within one year of the date of loss, and for a hurricane that is the landfall date: October 9, 2026. So notice is due by October 9, 2027. A supplemental claim, if the first payment falls short, gets 18 months.
Wind damage from a named storm is covered under the windstorm part of a standard Florida policy, subject to your hurricane deductible, which is usually 2 to 5 percent of your dwelling coverage rather than a flat number. Water that came in through the wind-damaged roof is normally part of the same loss.
It depends on what the inspection finds, and after a hurricane most of it should be the insurer's cost, not yours, beyond the deductible. We give you an itemized scope before any work and the same scope goes to the carrier. We do not quote a number over the phone that the roof has not earned.
Not necessarily anymore. Since 2022, roofs built to the 2007 Florida Building Code or later can be repaired rather than replaced even when more than 25 percent is damaged. Older roofs may still fall under the full-replacement rule. We check the permit history on your roof at the inspection and tell you which side of the line you are on.
Usually, and when we cannot, we tell you before the work starts, because a mismatch is something the insurer's scope should address. We bring samples to the inspection.
We are a Florida company, veteran-owned and operated since 1977, with crews staged in Milton and Destin for the length of this recovery. We are not from Milton, and we will not pretend to be. What we will do is show up when we say, document everything, and build it to code.
Free roof inspection
Milton, Destin, Pensacola and everywhere in between. Tarp, repair, replacement, one crew.
Takes 30 seconds. A person calls you back, not a call center.
A real person answers, tells you what to do right now, and books a free roof inspection in Milton, Destin or Pensacola.
Call (850) 407-3140